Home Lifestyle NIGERIAN YOUNGSTER REDEFINING FINTECH – THISDAYLIVE
Lifestyle

NIGERIAN YOUNGSTER REDEFINING FINTECH – THISDAYLIVE

Share
Share

[ad_1]

By Tayo Ogunbiyi

Across continents, technology entrepreneurs are redefining how individuals and businesses send, receive, and manage money in an increasingly connected digital economy.

In recent years, Nigeria has earned global recognition as one of Africa’s leading technology hubs. From financial technology and e-commerce to artificial intelligence and software development, Nigerian innovators have consistently demonstrated an ability to solve complex problems through creative and scalable solutions.

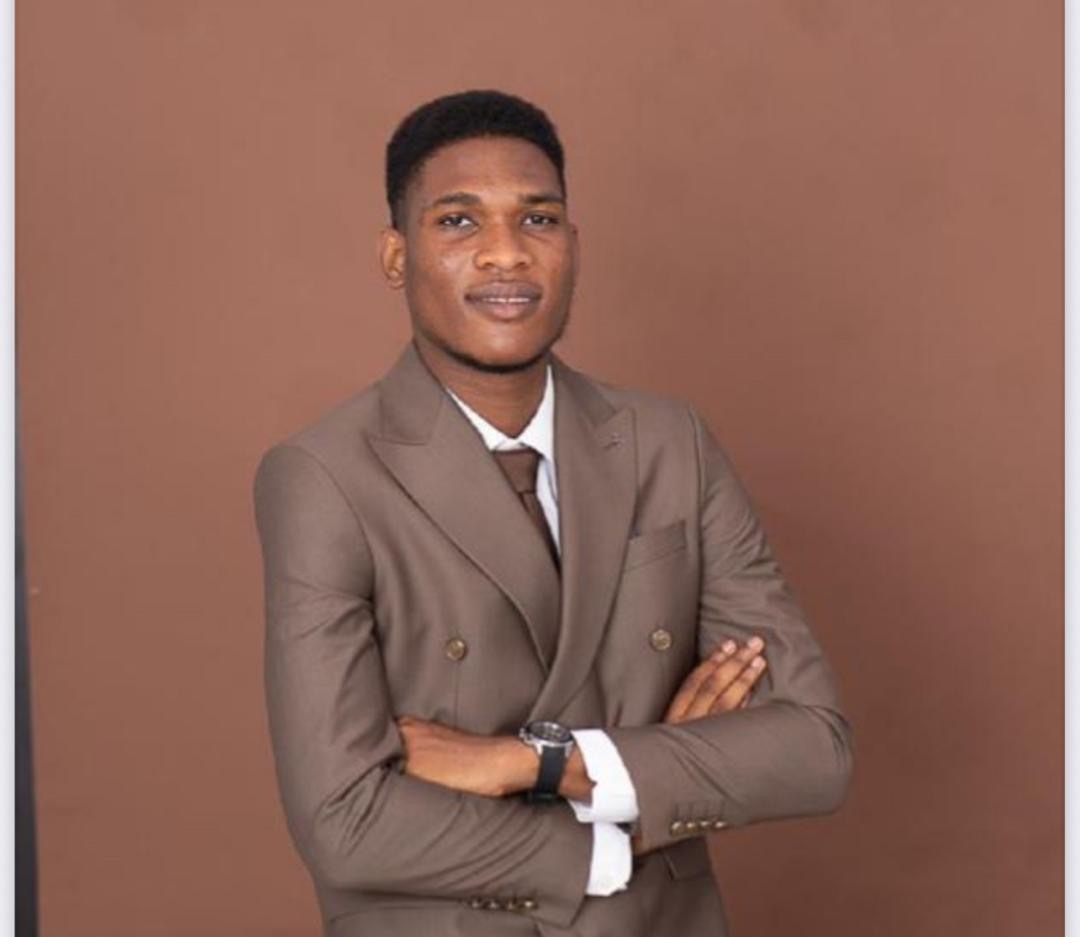
Among the rising innovators helping to shape this new era is Oluwasemilore Emmanuel Aina, a young Nigerian founder whose work with Paylinc is attracting attention within international fintech circles.

Through a combination of technological innovation, strategic thinking, and an ambitious vision for digital financial inclusion, Oluwasemilore is building a platform that seeks to bridge gaps in modern payment systems while creating new opportunities for users across multiple markets.

His journey reflects a broader story that is increasingly becoming familiar across the global technology landscape: the rise of Nigerian entrepreneurs whose innovations are competing on the world stage and demonstrating that Africa is not merely consuming technology but actively creating it.

Often described by industry observers as a Paylinc expert, this young entrepreneur has distinguished himself through his deep understanding of payment infrastructure and digital transaction systems.

His expertise extends beyond simply developing software. It involves understanding the complex intersection of technology, user behavior, compliance requirements, security protocols, and financial regulations that shape the modern fintech ecosystem.

The financial technology sector is one of the most competitive industries in the world today. New startups emerge regularly, while established financial institutions continue investing heavily in digital transformation initiatives. In such an environment, standing out requires more than technical competence; it demands innovation, adaptability, and a clear understanding of emerging market needs.

This is where Paylinc seeks to carve out its niche. At its core, Paylinc represents an attempt to simplify and enhance financial interactions in a world where cross-border transactions remain challenging for many users.

Despite tremendous advances in digital banking and payment technology, millions of people and businesses still encounter obstacles when moving money internationally. These challenges often include high transaction fees, lengthy processing times, limited accessibility, and regulatory complexities.

By focusing on digital efficiency and user-centered experiences, Paylinc aims to address some of these longstanding challenges while creating an ecosystem that encourages participation and engagement.

What makes the platform particularly interesting to industry watchers is its operational structure. Unlike many traditional payment platforms that focus exclusively on transaction processing, Paylinc integrates payment functionality with a broader referral-based ecosystem designed to stimulate organic growth and user participation.

This approach has generated considerable interest within fintech communities because it combines elements of payment technology, digital networking, and community engagement into a single framework.

Industry analysts often describe the model as innovative yet inherently complex. The reason lies in the reality that modern fintech platforms operate within a highly regulated environment where compliance, security, transparency, and operational integrity are essential.

Building any financial platform requires careful navigation of evolving regulations, cybersecurity risks, consumer protection requirements, anti-money laundering obligations, and data privacy standards. These considerations become even more important when a platform seeks to operate across different jurisdictions and international markets.

The platform’s evolution has also drawn comparisons with some of the early pioneers of modern fintech. During the formative years of financial technology, companies such as Plaid helped transform the industry by creating infrastructure that connected financial institutions with emerging digital applications.

Those early innovators operated during a period when digital banking integrations were still developing, and financial APIs had not yet become mainstream.

Today’s fintech environment is significantly different.

The sector now faces stricter regulatory oversight, more sophisticated cybersecurity threats, increased competition, and higher customer expectations. Users demand seamless experiences, instant transactions, and strong protection of their personal information. As a result, modern fintech founders must navigate a far more complex environment than many of their predecessors.

Yet it is precisely within these challenges that opportunities emerge. For Paylinc, one of the most significant drivers of growth has been its Referral Programme. While referral systems are not new to the technology industry, Paylinc’s approach has become a defining feature of its expansion strategy.

Rather than functioning solely as a traditional incentive mechanism, the programme has evolved into a broader engagement ecosystem that encourages users to become active participants in the platform’s growth.

The concept is built around a simple principle: people are more likely to trust recommendations that come from individuals they know. By leveraging community relationships and user advocacy, the platform has been able to increase awareness while creating a sense of shared participation among its growing user base.

This community-oriented strategy aligns with broader trends across the technology sector. In an era where customer acquisition costs continue to rise, many successful companies are investing heavily in trust-based growth models that emphasize authentic engagement and long-term user relationships.

For fintech companies in particular, trust remains one of the most valuable assets. Unlike many digital products, where users face minimal risk, financial platforms are responsible for handling sensitive information and facilitating monetary transactions. Consequently, users are often more cautious when adopting new financial technologies.

Industry experts suggest that platforms capable of combining technological reliability with strong community trust may enjoy a significant competitive advantage in the years ahead.

The founder’s journey also highlights the growing influence of Nigerian technology professionals on the global stage. Over the last decade, Nigerian founders, developers, engineers, and product designers have contributed to some of the world’s most innovative startups and technology companies.

International investors increasingly view Nigeria as a source of high-quality entrepreneurial talent capable of building globally relevant solutions. This shift in perception has helped create new opportunities for Nigerian innovators seeking to scale their ventures beyond domestic markets.

The success stories emerging from Nigeria’s technology ecosystem continue to inspire younger generations to pursue careers in entrepreneurship, software development, product innovation, and digital business.

For many aspiring founders, the rise of platforms like Paylinc demonstrates that geographic boundaries are becoming less significant in determining entrepreneurial success. With access to technology, talent, and global markets, innovators can now build products that compete internationally regardless of where they begin.

As digital finance continues evolving, the future will likely belong to platforms capable of adapting quickly to changing user needs, regulatory developments, and technological advancements.

Artificial intelligence, blockchain technology, embedded finance, open banking, and decentralized financial systems are expected to reshape the industry further over the coming years. Founders who successfully navigate these shifts while maintaining strong user trust will be best positioned to thrive in the next phase of fintech innovation.

For this young Nigerian entrepreneur behind Paylinc, the mission appears to extend beyond building another payment platform.
It is about creating a system that connects people, expands opportunities, encourages participation, and reimagines how digital financial communities can grow in an interconnected world.

Whether Paylinc ultimately becomes a major player in the global fintech sector remains to be seen. However, its emergence reflects an important reality: Nigerian innovation continues to expand its footprint internationally, driven by ambitious founders determined to create solutions that transcend borders.

In a rapidly changing digital economy, that ambition may prove to be one of the most valuable currencies of all.

• Ogunbiyi is Director, Public Enlightenment & Community Relations, Ministry of Information & Strategy, Alausa, Ikeja, Lagos.

[ad_2]

Source link
Share

Leave a comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Related Articles

Golden Penny Rewards Dealers at 2026  Dealers and Sales Conference – THISDAYLIVE

[ad_1] * Unveils new Golden Penny Penne 500g Golden Penny Foods, the...

Odukoya Memorial Lecture to  Focus on  Nigeria’s Leadership Crisis – THISDAYLIVE

[ad_1] Mary Nnah Lagos is set to host what organisers call a...

UNICAL Alumni Take Voter Registration Awareness Campaign to Abuja Markets – THISDAYLIVE

[ad_1] Olawale Ajimotokan  in Abuja  The University of Calabar Graduates Elite Club...

Outspan Spotlights Women Dairy Farmers, Local Value Chain Growth in Kano – THISDAYLIVE

[ad_1] Precious Ugwuzor  Outspan Nigeria Limited, a subsidiary of olam food ingredients (ofi),...

news-1701

yakinjp

yakinjp

maujp

TOTOMACAU

sabung ayam online

sabung ayam online

sabung ayam online

sabung ayam online

article 88888880

article 88888881

article 88888882

article 88888883

article 88888884

article 88888885

article 88888886

article 88888887

article 88888888

article 88888889

article 88888890

article 88888891

article 88888892

article 88888893

article 88888894

article 88888895

article 88888896

article 88888897

article 88888898

article 88888899

article 88888900

article 88888901

article 88888902

article 88888903

article 88888904

article 88888905

article 88888906

article 88888907

article 88888908

article 88888909

article 88888910

article 88888911

article 88888912

article 88888913

article 88888914

article 88888915

article 88888916

article 88888917

article 88888918

article 88888919

article 88888920

article 88888921

article 88888922

article 88888923

article 88888924

article 88888925

article 88888926

article 88888927

article 88888928

article 88888929

article 88888930

article 88888931

article 88888932

article 88888933

article 88888934

article 88888935

article 88888936

article 88888937

article 88888938

article 88888939

article 88888940

article 88888941

article 88888942

article 88888943

article 88888944

article 88888945

article 88888946

article 88888947

article 88888948

article 88888949

article 88888950

article 88888951

article 88888952

article 88888953

article 88888954

article 88888955

article 88888956

article 88888957

article 88888958

article 88888959

article 22220471

article 22220472

article 22220473

article 22220474

article 22220475

article 22220476

article 22220477

article 22220478

article 22220479

article 22220480

article 22220481

article 22220482

article 22220483

article 22220484

article 22220485

article 22220486

article 22220487

article 22220488

article 22220489

article 22220490

article 22220491

article 22220492

article 22220493

article 22220494

article 22220495

article 22220496

article 22220497

article 22220498

article 22220499

article 22220500

article 22220501

article 22220502

article 22220503

article 22220504

article 22220505

article 22220506

article 22220507

article 22220508

article 22220509

article 22220510

article 10000566

article 10000567

article 10000568

article 10000569

article 10000570

article 10000571

article 10000572

article 10000573

article 10000574

article 10000575

article 10000576

article 10000577

article 10000578

article 10000579

article 10000580

article 10000581

article 10000582

article 10000583

article 10000584

article 10000585

article 10000586

article 10000587

article 10000588

article 10000589

article 10000590

article 10000591

article 10000592

article 10000593

article 10000594

article 10000595

article 10000596

article 10000597

article 10000598

article 10000599

article 10000600

article 10000601

article 10000602

article 10000603

article 10000604

article 10000605

article 10000606

article 10000607

article 10000608

article 10000609

article 10000610

article 10000611

article 10000612

article 10000613

article 10000614

article 10000615

artikel 000000135

artikel 000000136

artikel 000000137

artikel 000000138

artikel 000000139

artikel 000000140

artikel 000000141

artikel 000000142

artikel 000000143

artikel 000000144

artikel 000000145

artikel 000000146

artikel 000000147

artikel 000000148

artikel 000000149

artikel 000000150

artikel 000000151

artikel 000000152

artikel 000000153

artikel 000000154

artikel 000000155

artikel 000000156

artikel 000000157

artikel 000000158

artikel 000000159

artikel 000000160

artikel 000000161

artikel 000000162

artikel 000000163

artikel 000000164

artikel 000000165

artikel 000000166

artikel 000000167

artikel 000000168

artikel 000000169

artikel 000000170

artikel 000000171

artikel 000000172

artikel 000000173

artikel 000000174

artikel 000000175

article 2000591

article 2000592

article 2000593

article 2000594

article 2000595

article 2000596

article 2000597

article 2000598

article 2000599

article 2000600

article 2000601

article 2000602

article 2000603

article 2000604

article 2000605

article 2000606

article 2000607

article 2000608

article 2000609

article 2000610

article 2000611

article 2000612

article 2000613

article 2000614

article 2000615

article 2000616

article 2000617

article 2000618

article 2000619

article 2000620

article 2000621

article 2000622

article 2000623

article 2000624

article 2000625

article 2000626

article 2000627

article 2000628

article 2000629

article 2000630

article 5500386

article 5500387

article 5500388

article 5500389

article 5500390

article 5500391

article 5500392

article 5500393

article 5500394

article 5500395

article 5500396

article 5500397

article 5500398

article 5500399

article 5500400

article 5500401

article 5500402

article 5500403

article 5500404

article 5500405

article 5500406

article 5500407

article 5500408

article 5500409

article 5500410

article 5500411

article 5500412

article 5500413

article 5500414

article 5500415

article 5500416

article 5500417

article 5500418

article 5500419

article 5500420

article 5500421

article 5500422

article 5500423

article 5500424

article 5500425

article 5500426

article 5500427

article 5500428

article 5500429

article 5500430

article 5500431

article 5500432

article 5500433

article 5500434

article 5500435

article 5500436

article 5500437

article 5500438

article 5500439

article 5500440

article 5500441

article 5500442

article 5500443

article 5500444

article 5500445

article 5500446

article 5500447

article 5500448

article 5500449

article 5500450

article 5500451

article 5500452

article 5500453

article 5500454

article 5500455

article 838000838

article 838000839

article 838000840

article 838000841

article 838000842

article 838000843

article 838000844

article 838000845

article 838000846

article 838000847

article 838000848

article 838000849

article 838000850

article 838000851

article 838000852

article 838000853

article 838000854

article 838000855

article 838000856

article 838000857

article 838000858

article 838000859

article 838000860

article 838000861

article 838000862

article 838000863

article 838000864

article 838000865

article 838000866

article 838000867

article 838000868

article 838000869

article 838000870

article 838000871

article 838000872

article 838000873

article 838000874

article 838000875

article 838000876

article 838000877

article 838000878

article 838000879

article 838000880

article 838000881

article 838000882

article 838000883

article 838000884

article 838000885

article 838000886

article 838000887

article 838000888

article 838000889

article 838000890

article 838000891

article 838000892

article 838000893

article 838000894

article 838000895

article 838000896

article 838000897

article 838000898

article 838000899

article 838000900

article 838000901

article 838000902

article 9998000751

article 9998000752

article 9998000753

article 9998000754

article 9998000755

article 9998000756

article 9998000757

article 9998000758

article 9998000759

article 9998000760

article 9998000761

article 9998000762

article 9998000763

article 9998000764

article 9998000765

article 9998000766

article 9998000767

article 9998000768

article 9998000769

article 9998000770

article 9998000771

article 9998000772

article 9998000773

article 9998000774

article 9998000775

article 9998000776

article 9998000777

article 9998000778

article 9998000779

article 9998000780

article 9998000781

article 9998000782

article 9998000783

article 9998000784

article 9998000785

article 9998000786

article 9998000787

article 9998000788

article 9998000789

article 9998000790

article 9998000791

article 9998000792

article 9998000793

article 9998000794

article 9998000795

article 9998000796

article 9998000797

article 9998000798

article 9998000799

article 9998000800

article 9998000801

article 9998000802

article 9998000803

article 9998000804

article 9998000805

article 9998000806

article 9998000807

article 9998000808

article 9998000809

article 9998000810

article 9998000811

article 9998000812

article 9998000813

article 9998000814

article 9998000815

article 66666669901

article 66666669902

article 66666669903

article 66666669904

article 66666669905

article 66666669906

article 66666669907

article 66666669908

article 66666669909

article 66666669910

article 66666669911

article 66666669912

article 66666669913

article 66666669914

article 66666669915

article 66666669916

article 66666669917

article 66666669918

article 66666669919

article 66666669920

article 66666669921

article 66666669922

article 66666669923

article 66666669924

article 66666669925

article 66666669926

article 66666669927

article 66666669928

article 66666669929

article 66666669930

article 66666669931

article 66666669932

article 66666669933

article 66666669934

article 66666669935

article 66666669936

article 66666669937

article 66666669938

article 66666669939

article 66666669940

news-1701